
Using cards during personal rehabilitation: rules for credit cards and debit cards
Credit cards are mostly blocked, while debit cards can still be used. We have gathered, question by question, what people preparing for or going through personal rehabilitation (gaein hoesaeng) ask most often about using cards.
Can I still use a credit card after applying for personal rehabilitation? Is a debit card all right?
Can I keep using my credit card?
In most cases, it is difficult. Once an application for personal rehabilitation is filed, financial institutions often restrict or suspend card use after checking for delinquency and the fact of the application.
Credit cards you were already using may also be subject to measures such as suspension of use, a reduced limit, or cancellation. If you are going through personal rehabilitation, it is safer to prepare on the assumption that you cannot use credit cards.
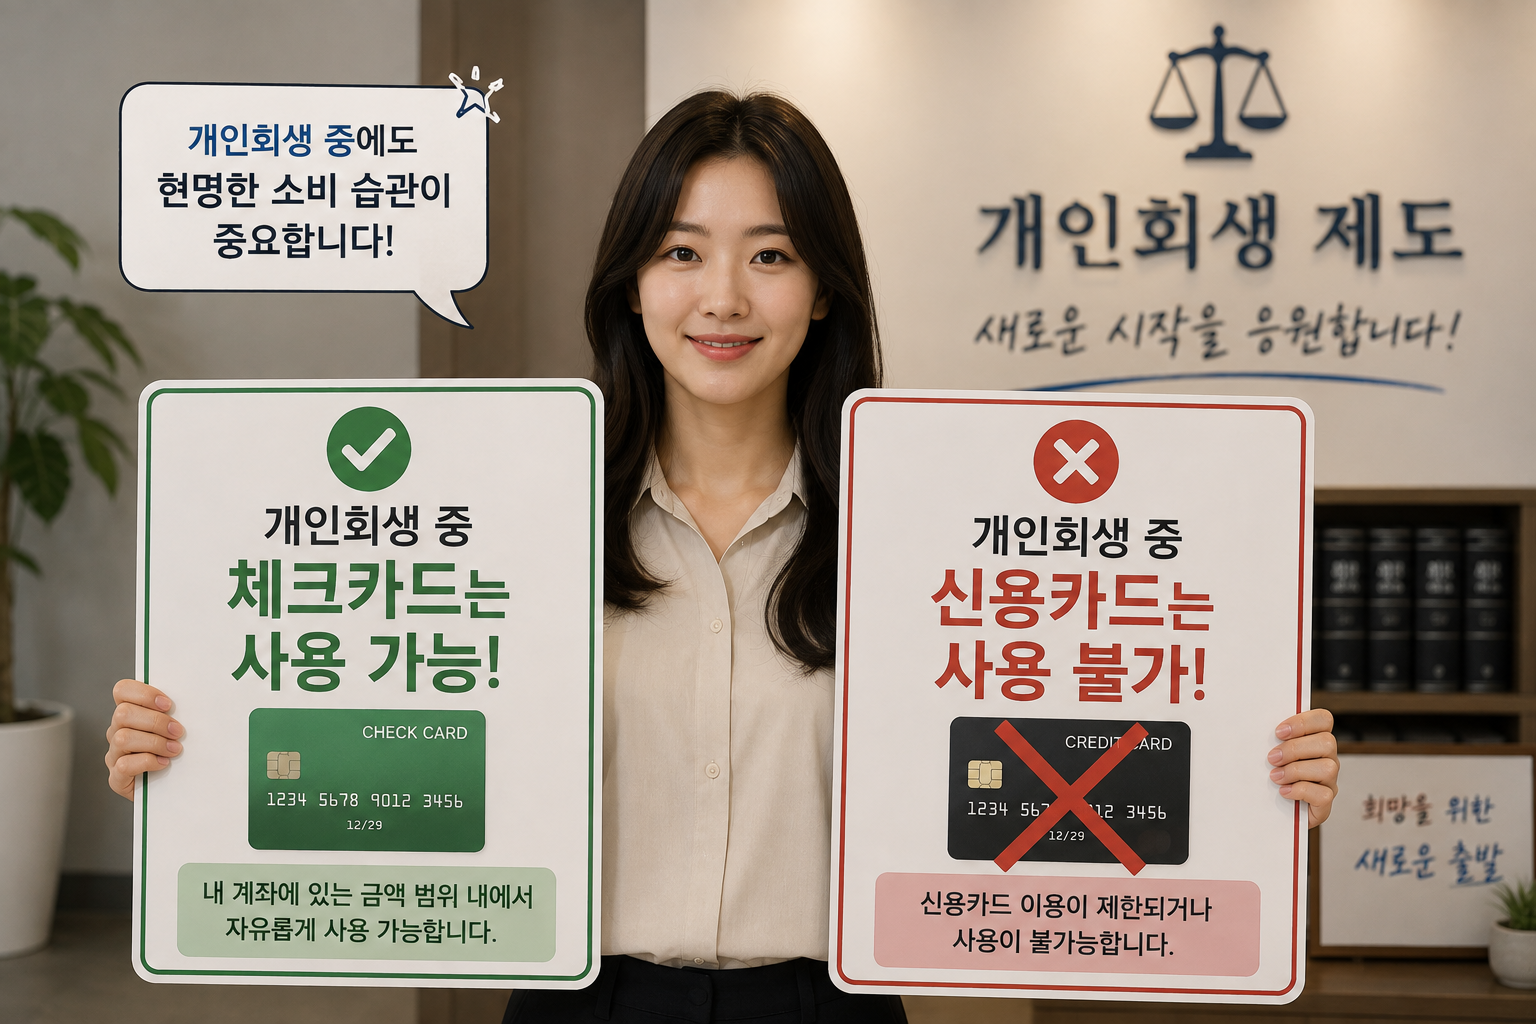
Debit cards can be used as before
You can continue using a debit card. A debit card only makes payments within the balance of your own account, so it is different in nature from a credit card, which uses borrowed credit. It is usually linked to a salary account or an account for living expenses.
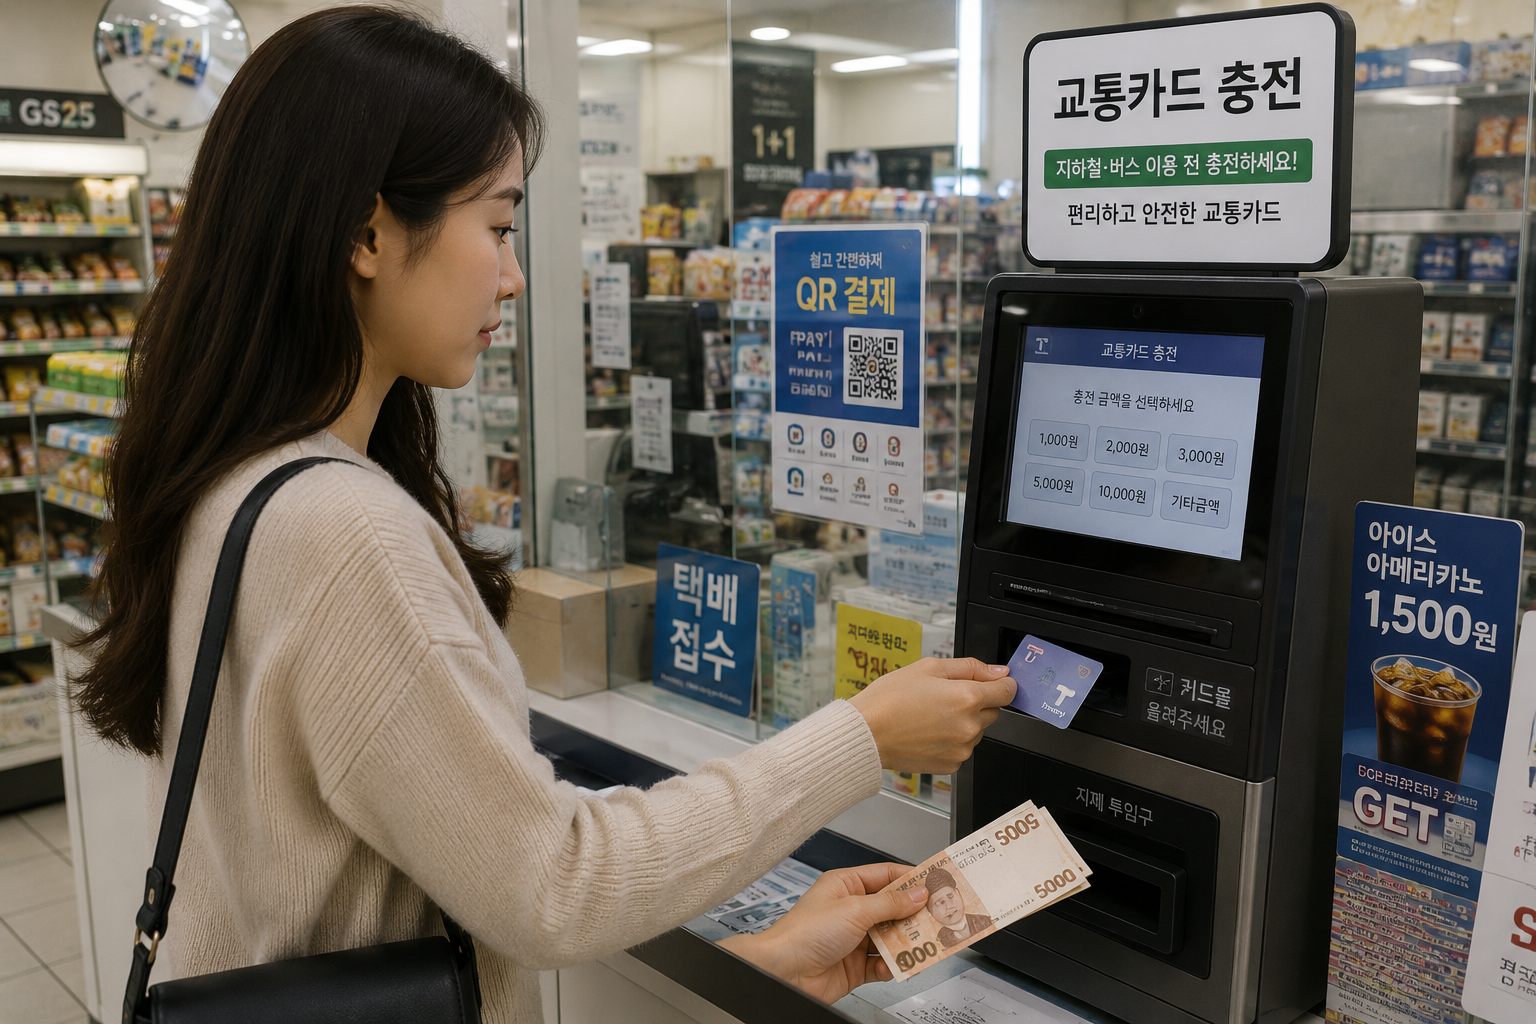
Payments that were tied to a credit card, such as bus and subway transit cards and Hi-pass toll payments, should all be switched to a debit card or a prepaid card.
Card use right before applying is the most risky
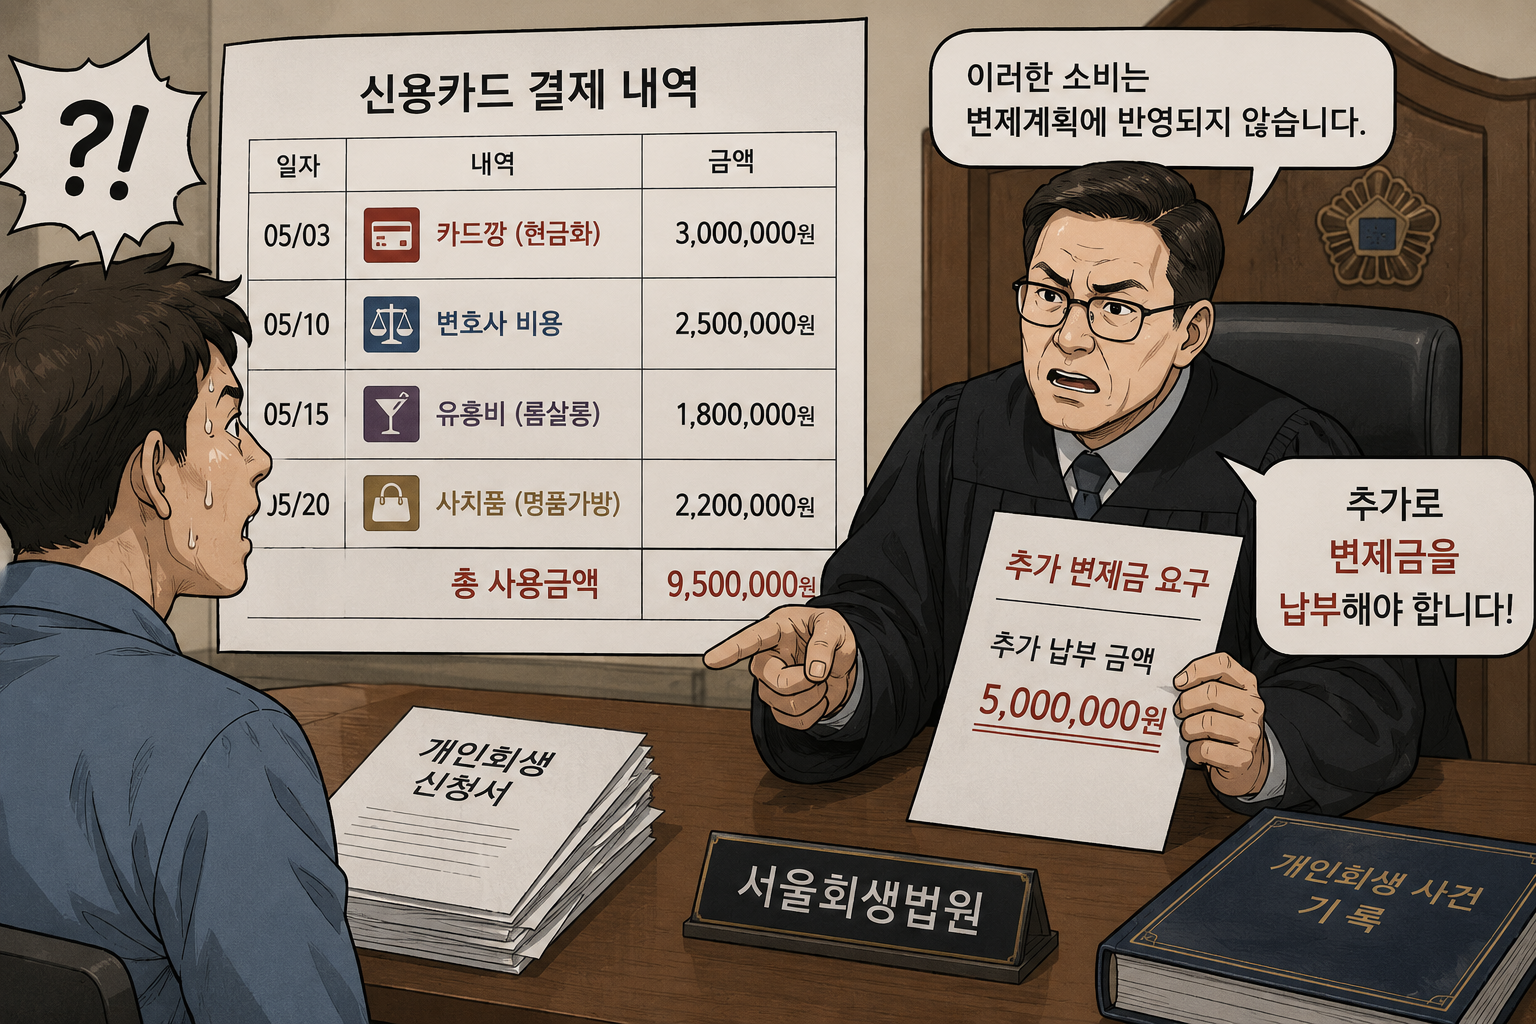
If you use cards as below ahead of personal rehabilitation, the court may check how that money was used.
- Using cards up to the limit
- Cash advances
- Card loans
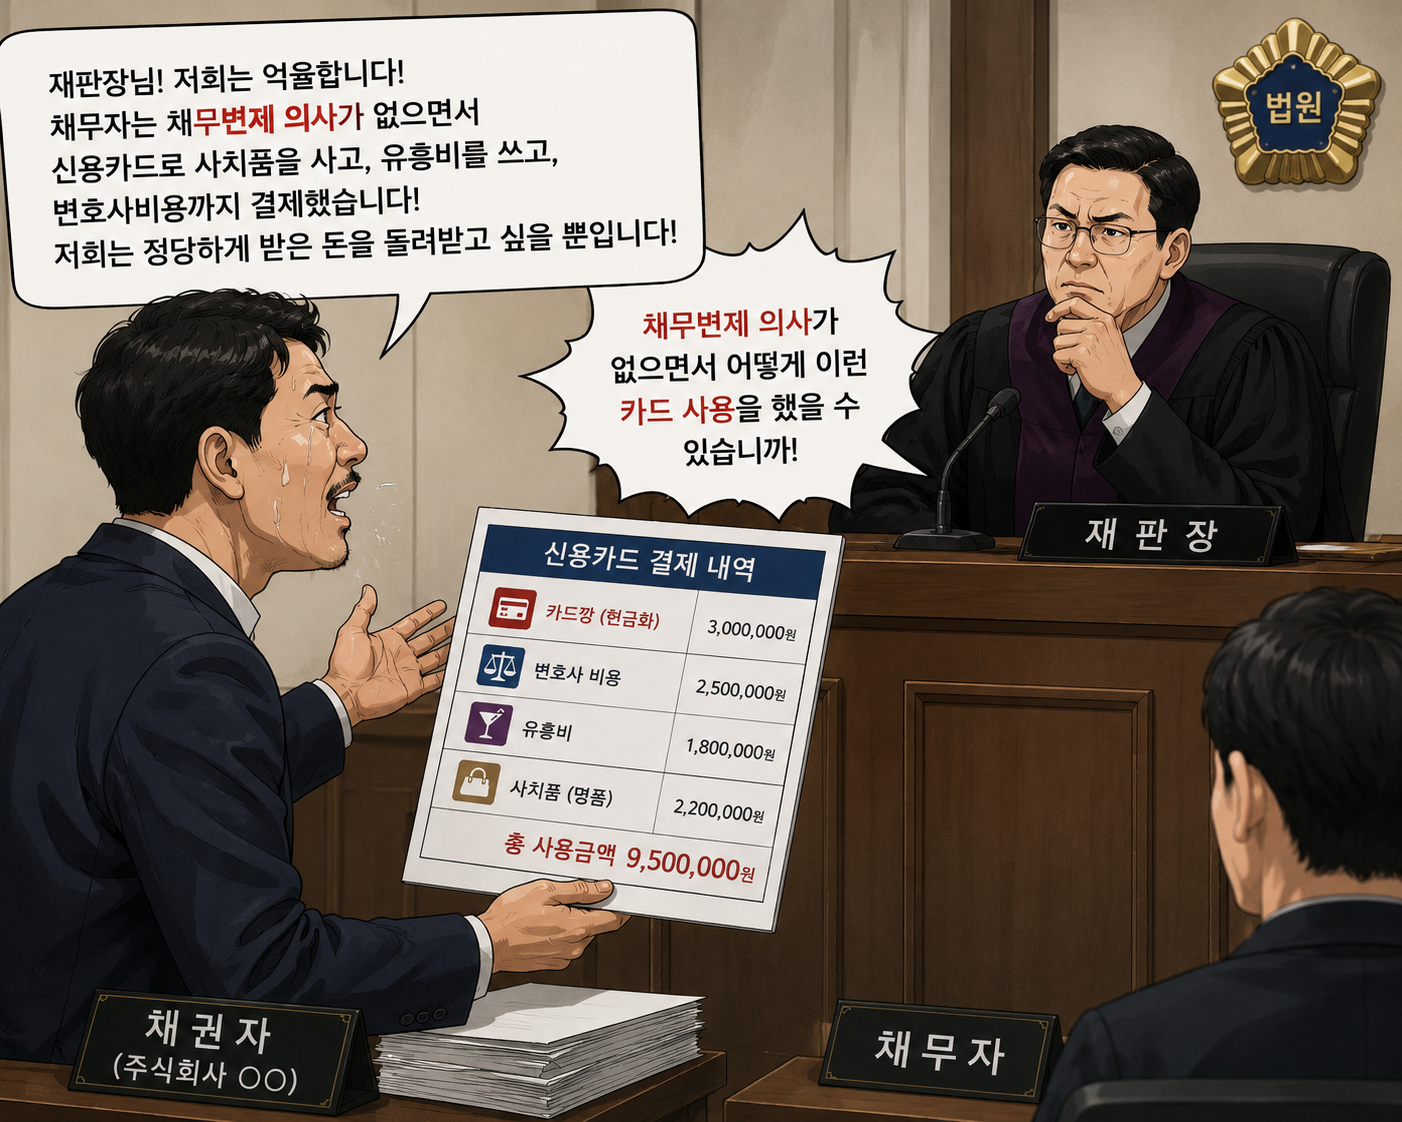
If you used cards excessively or took out loans right before applying, you may have to separately explain how the debt arose. In some cases you may also be asked to reflect amounts spent right before rehabilitation in the liquidation value.
What should I use to pay for living expenses?
During personal rehabilitation, it is common to pay living expenses by debit card, cash or bank transfer. The court may later look at where you spent your living expenses, so manage them as transparently as possible.
Avoid card use like this
- Using a credit card up to the limit
- Card loans or cash advances
- Getting a new credit card issued
- Using a card in someone else's name
- Buying more things when you have no ability to repay
Such actions can lead to unnecessary explanations or correction requests during personal rehabilitation, so be careful.
Can I get a new credit card during personal rehabilitation?
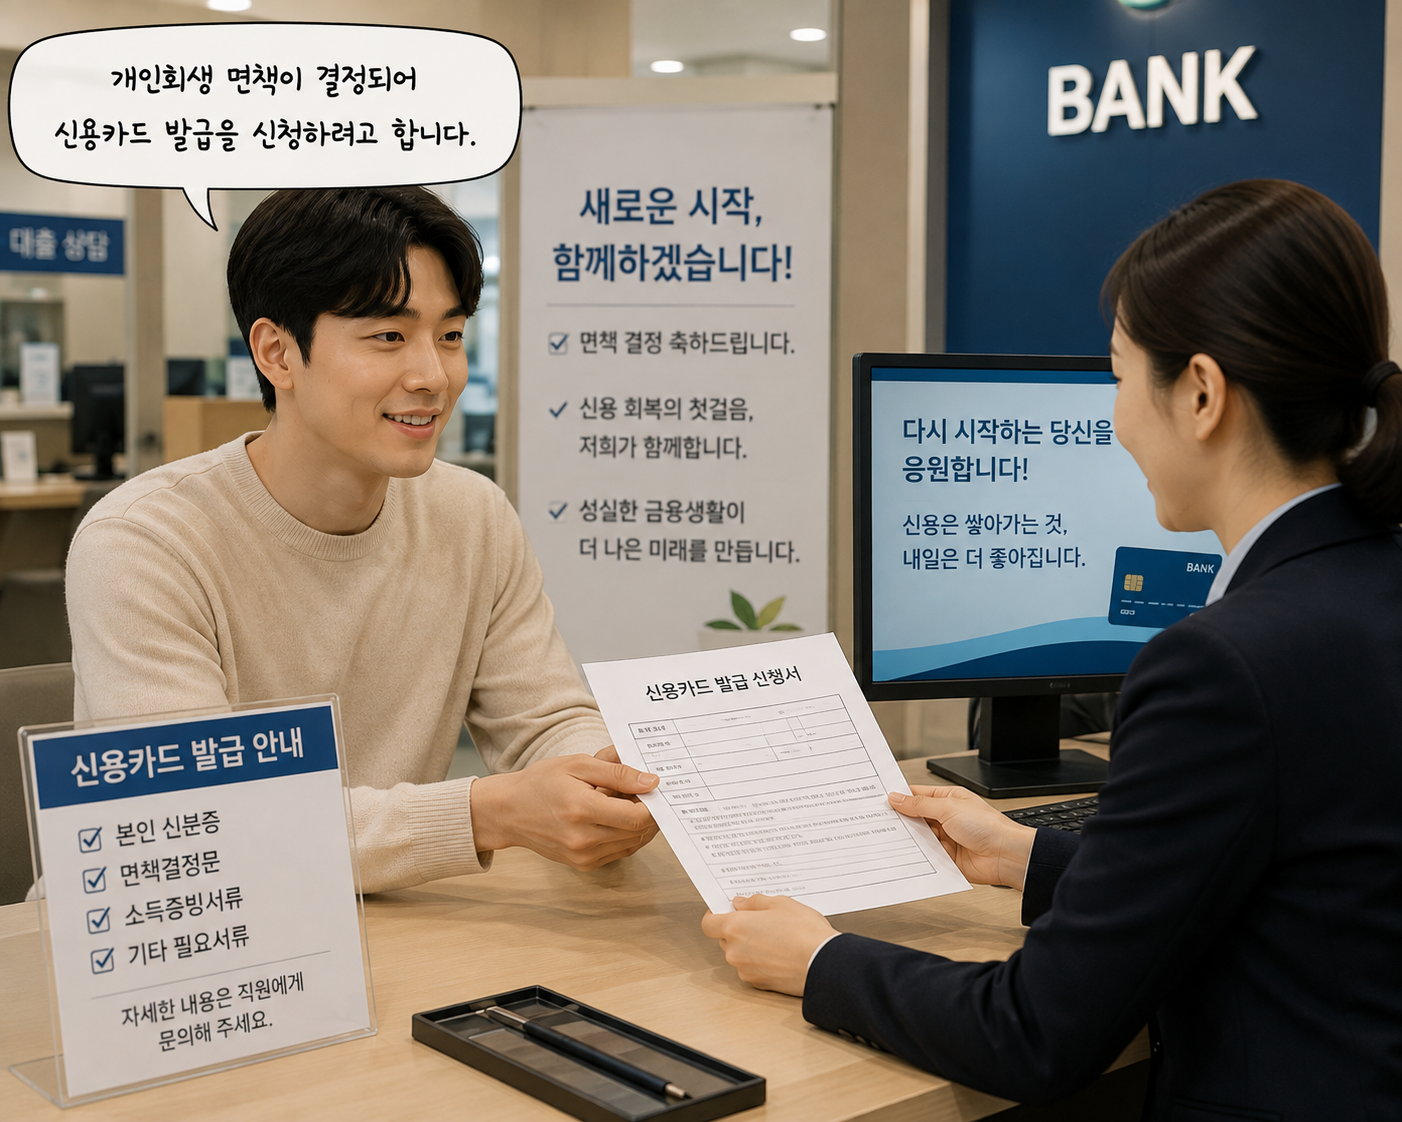
It is difficult. While the personal rehabilitation procedure is underway or while you are carrying out the repayment plan, your creditworthiness is rated low, so most financial institutions restrict the issuance of credit cards. After you receive a discharge and your credit recovers, you can apply for a card again subject to the financial institution's review.
Other frequently asked questions
Can my debit card be seized? It is not the debit card itself but the account linked to the debit card that can be subject to seizure.
Will automatic transfers keep going out? Withdrawals may continue from the account where the automatic transfers are set up. Be sure to check your list of automatic transfers before applying.
Can I use a family card? If you keep using a credit card in a family member's name, an explanation may be needed depending on the circumstances, so it is best to use it with care.
It is not a procedure that ends once you submit the application
Personal rehabilitation is not a procedure that is wrapped up by filing a single document. Reviewing your card usage history, the flow of funds, and any recent loans before applying helps reduce later correction orders or requests for additional explanation. This shows how important the preparation stage is.
Our office carries out the personal rehabilitation procedure together with the client according to their circumstances, from consultation and document preparation before applying to the correction process, plan confirmation and discharge.
Summary
Once you start personal rehabilitation, credit card use is mostly blocked and you will live mainly on a debit card. Card use, card loans and cash advances right before applying are areas the court looks into, so be careful. Rather than worrying alone, we recommend first reviewing an approach that fits your current card use and debt situation.
Last reviewed: 2026-10-19 This article provides general legal information; specific advice is given through consultation.
Tell us what is happening first
Leave an inquiry and we will explain how to proceed after reviewing it. If it is urgent, please call 1577-0448.