
Insurance claims, from filing to court, in one office
Our loss adjusters handle the claim, and if the insurer refuses or cuts it, a lawyer in the same office takes it forward.
Why one office
Loss adjusters based in our office handle your insurance claim. If the insurer refuses to pay or reduces the amount, a lawyer in the same office continues through negotiation and, if needed, litigation.
Loss adjuster
Investigates the accident and the loss, calculates the amount, organises the documents and files the claim with the insurer. Also makes submissions to the insurer.
Lawyer
If the insurer refuses or reduces payment, the lawyer negotiates and, if that fails, takes the matter to court. Legal questions such as interpreting the policy terms are also the lawyer's.
Insurance matters we handle
Insurance claims
Permanent disability benefits: Where impairment remains after treatment, we document its extent and its link to the accident, including medical certificates, and file the claim.
Cancer, stroke & heart diagnosis benefits: When a diagnosis benefit for cancer, cerebrovascular or heart disease is refused or reduced, we review the diagnosis and the policy terms together.
Disclosure-breach disputes: We handle cases where the insurer refuses payment or cancels the policy on the ground that something was not disclosed before the contract.
Accident compensation
Motor insurance: After a traffic accident, we check whether the insurer's offer is fair, item by item: treatment costs, lost earnings and compensation for distress.
Liability insurance: When harm to another person needs to be handled through liability insurance, we review the scope of cover and the amount of loss.
Workplace injury
Industrial accident compensation: We handle workers' compensation applications and disability grading for accidents at work and occupational illness.
Employer's liability insurance: Separately from state workers' compensation, we review claims under the employer's liability insurance taken out by the business.
Serious workplace accidents: When a serious workplace accident occurs, we look at the compensation claim together with the legal issues that need a response.
Who this is for
Your claim was refused or reduced
We check whether the insurer's reason for refusing or cutting the payment fits the policy terms.
You were told the policy is cancelled for non-disclosure
We look at what was supposedly not disclosed and when, and whether it can be contested.
You disagree with your disability grade
We re-examine the degree of impairment using medical certificates and records.
Your workers' compensation claim was rejected
We review the reasons for rejection and explain the procedures available to challenge it.
How it works
- 1
Consultation
Understanding your accident and policy
We hear how the accident happened, what cover is in place and where the claim stands, then explain what is needed.
- 2
Loss adjustment
Review and filing
Our loss adjuster reviews the records, decides what to claim, and prepares and files the claim with the insurer.
- 3
Negotiation
Submissions and settling the amount
We respond to the insurer's assessment and negotiate the amount to be paid.
- 4
Litigation
If the insurer will not accept
If the insurer does not accept, a lawyer in the same office takes the matter to court.
Documents to prepare
What you need varies by case. If you have the following, please bring them to the first consultation.
Medical records
Medical certificates and doctors' opinions, receipts and itemised statements of medical expenses
Accident records
Records that show how the accident happened, such as an accident report certificate and photos of the scene
Insurance documents
The policy certificate and terms, and any refusal or reduction notice from the insurer
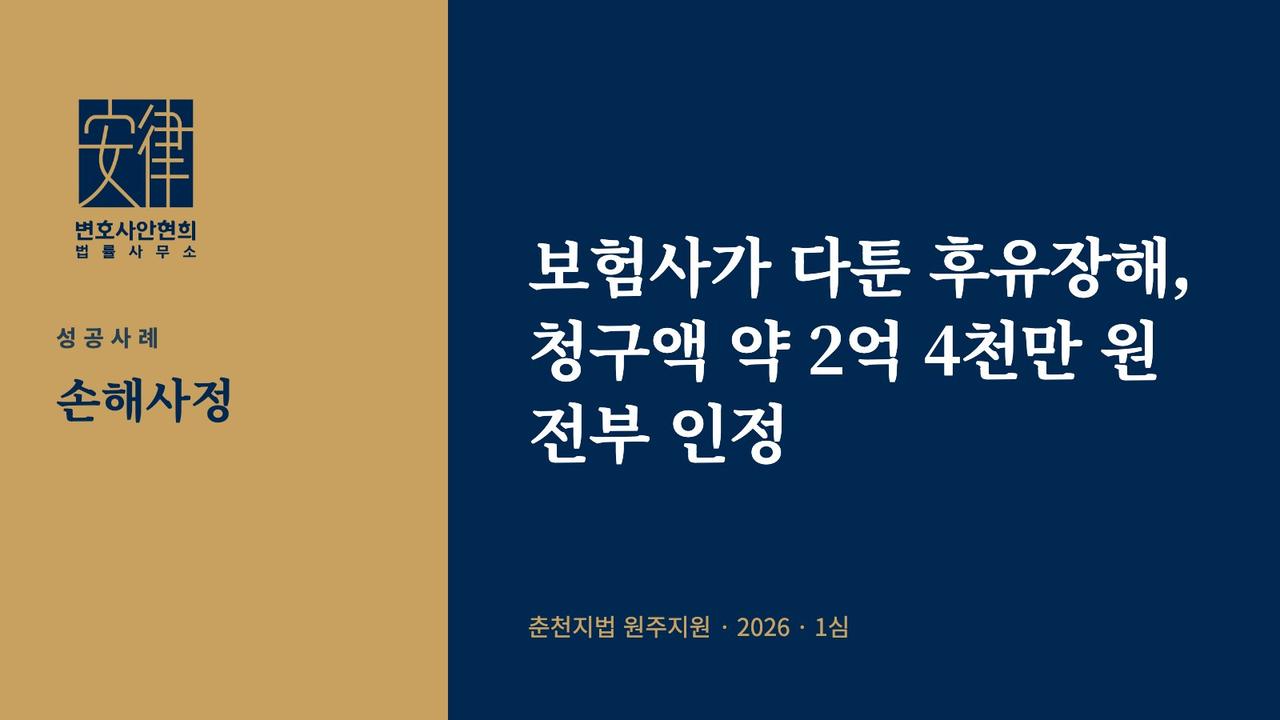
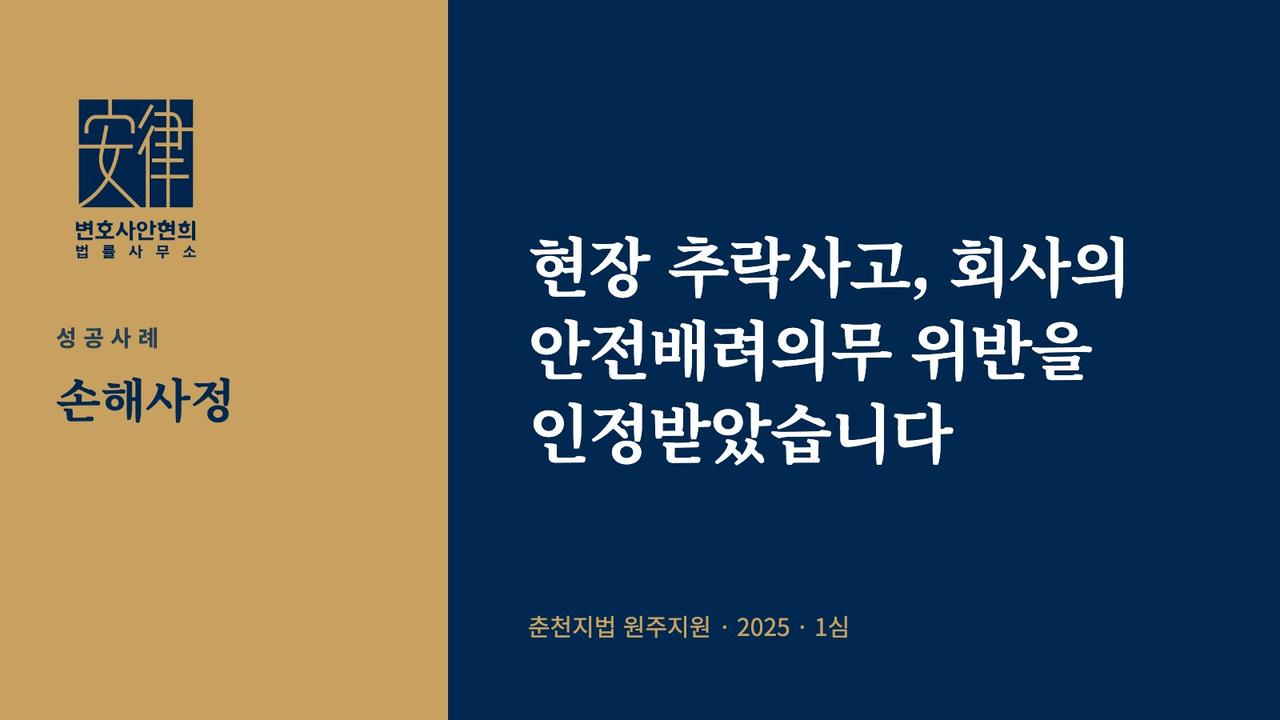
Loss adjustment success stories
Outcomes in this field, as confirmed by the courts' judgments.
Frequently asked questions
Should I accept the settlement the insurer offers straight away?
The insurer's figure may not reflect your own circumstances. Once you settle early, later after-effects or further conditions may not be covered, so it is better to look first at any permanent disability and the heads of claim.
The insurer has its own loss adjusters. Do I need a separate one?
If you do not accept the assessment made by the insurer's adjuster, you can choose your own loss adjuster. The assessed loss may change once an independent adjustment is made.
Can I claim again after a refusal?
You can resubmit and have the claim reviewed again, but it is not easy. That is why it matters to prepare the necessary documents and steps properly from the first claim.
I was injured at work. What compensation is available?
If the injury is recognised as work-related, industrial accident insurance provides medical care benefits and temporary disability benefits, and disability benefits if impairment remains after treatment. In the event of death, survivors' benefits and funeral expenses are paid. Serious injury or death cases can also involve settlement with the employer and civil or criminal issues, which we review together.
What heads of damages apply in a traffic accident claim?
They fall broadly into positive damages (actual outlays such as medical costs), passive damages (lost income such as lost earnings and loss from time off work) and non-pecuniary damages (compensation for distress). The amount depends on occupation, income, age, the degree of permanent disability and future treatment and care costs.
What documents do I need to claim permanent disability benefits?
You need medical records that show the link between the accident and the impairment, such as a medical certificate and a disability assessment. The documents vary by case, so we confirm them with you at the consultation.
Before you proceed
Three-year limitation period
A claim for insurance money expires if not exercised for three years (Commercial Act, Article 662). When the period starts depends on the case, so it is best to check early.
Check before signing
Signing a settlement or release presented by the insurer can make it hard to claim later for after-effects that appear afterwards. Check the content and scope before you sign.
Keep disclosure records as they are
Where non-disclosure is in dispute, altering or adding to documents yourself can work against you. Bring them as they are to the consultation.
Tell us what is happening first
Leave an inquiry and we will explain how to proceed after reviewing it. If it is urgent, please call 1577-0448.