
Personal rehabilitation after failed stock investments: the court’s review and the statement of how the debt increased
Quite a few people believe that debt from failed stock investments is not eligible for personal rehabilitation (gaein hoesaeng). In fact, you can apply. However, the court often reviews it more closely than debt incurred for living expenses, so we have summarized what the court looks at and how to prepare.
In recent years, the number of people seeking personal rehabilitation consultations after suffering large losses in domestic and overseas stocks and leveraged investments has risen sharply. The first questions asked in consultation are usually similar.
Does money lost on stocks qualify for personal rehabilitation? Isn't debt from investing excluded from rehabilitation?
Debt from failed stock investments is also eligible for personal rehabilitation
You can apply for personal rehabilitation even if you put bank loans or credit card funds into stocks and suffered losses. Debts arising from the following transactions can also be covered.
- Domestic and overseas stocks
- ETFs
- Leveraged and inverse products
- Margin loans and unsettled (credit) trading
The situations we see in consultation vary. Personal rehabilitation is proceeding in cases of investing with a personal loan or an overdraft account, drawing on credit card cash advances, suffering losses in overseas stocks or leveraged ETFs, and losing a large sum at once through forced liquidation.
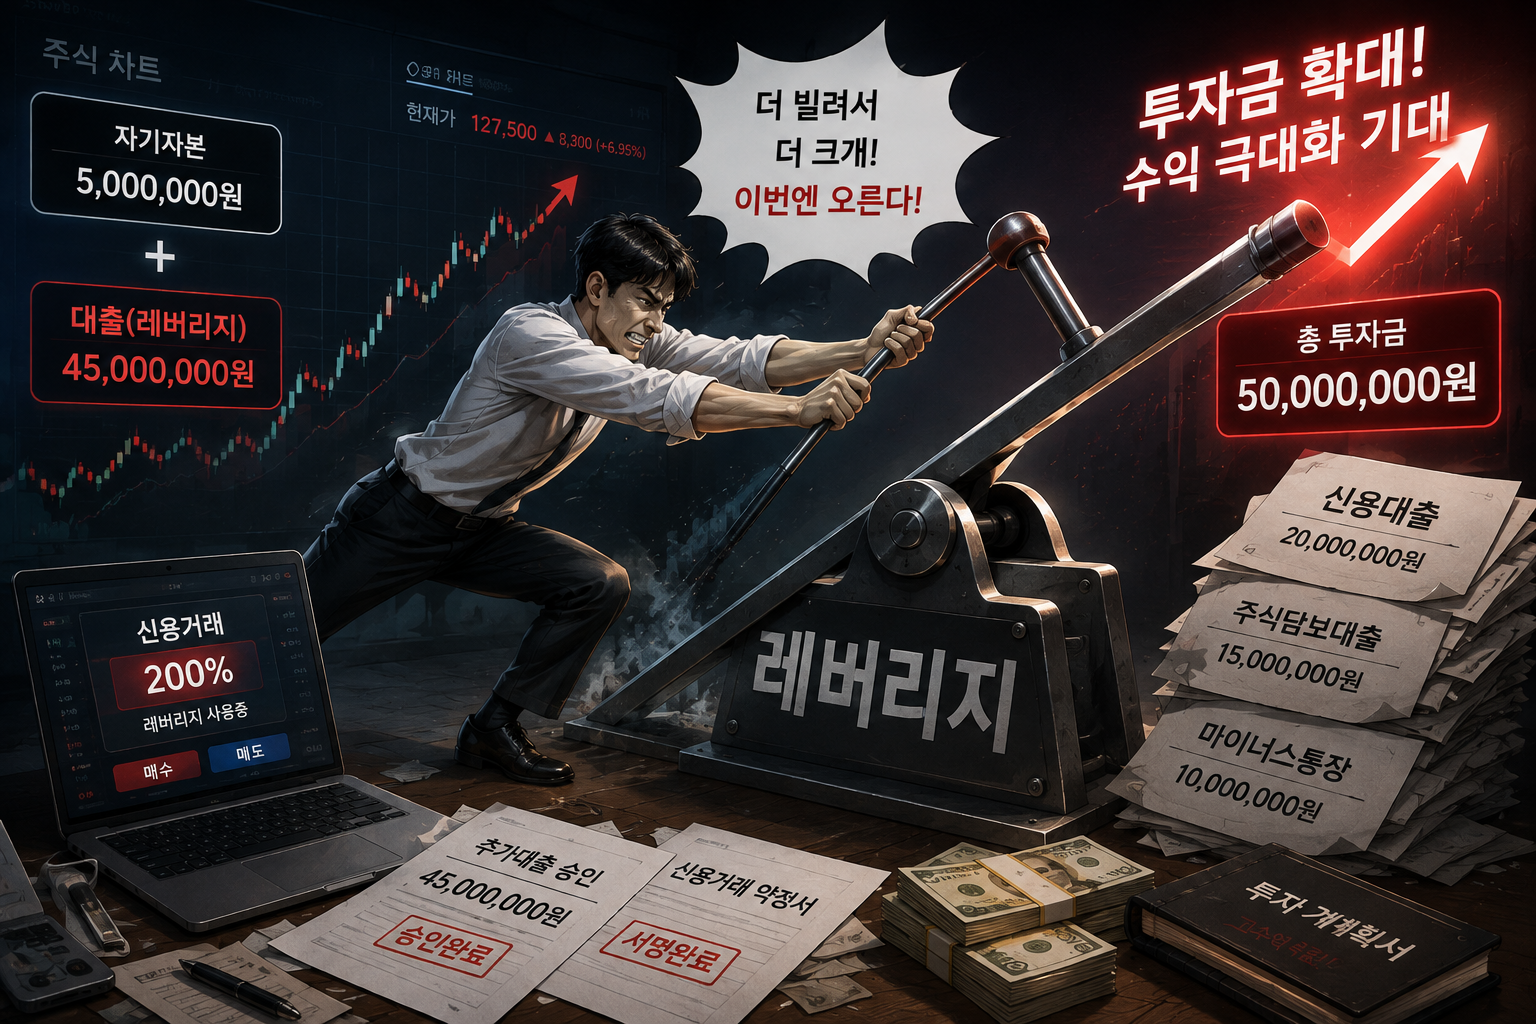
Four things the court examines in its review
The mere fact that you invested in stocks does not block personal rehabilitation. The court looks at the following together.
- When the debt arose. The court looks at whether the debt suddenly ballooned recently. Debt incurred within the last year is likely to be reflected in the liquidation value, and the monthly repayment may rise accordingly.
- Size of the investment. The court looks at whether the investment was excessively reckless relative to income.
- Current income. The court looks at whether you can faithfully keep to the repayment plan going forward. If your income is lower than at the job you had right before rehabilitation, this is reviewed more closely.
- How the investment came about. The court looks at whether it was a single failed stock investment or repeated speculative trading.
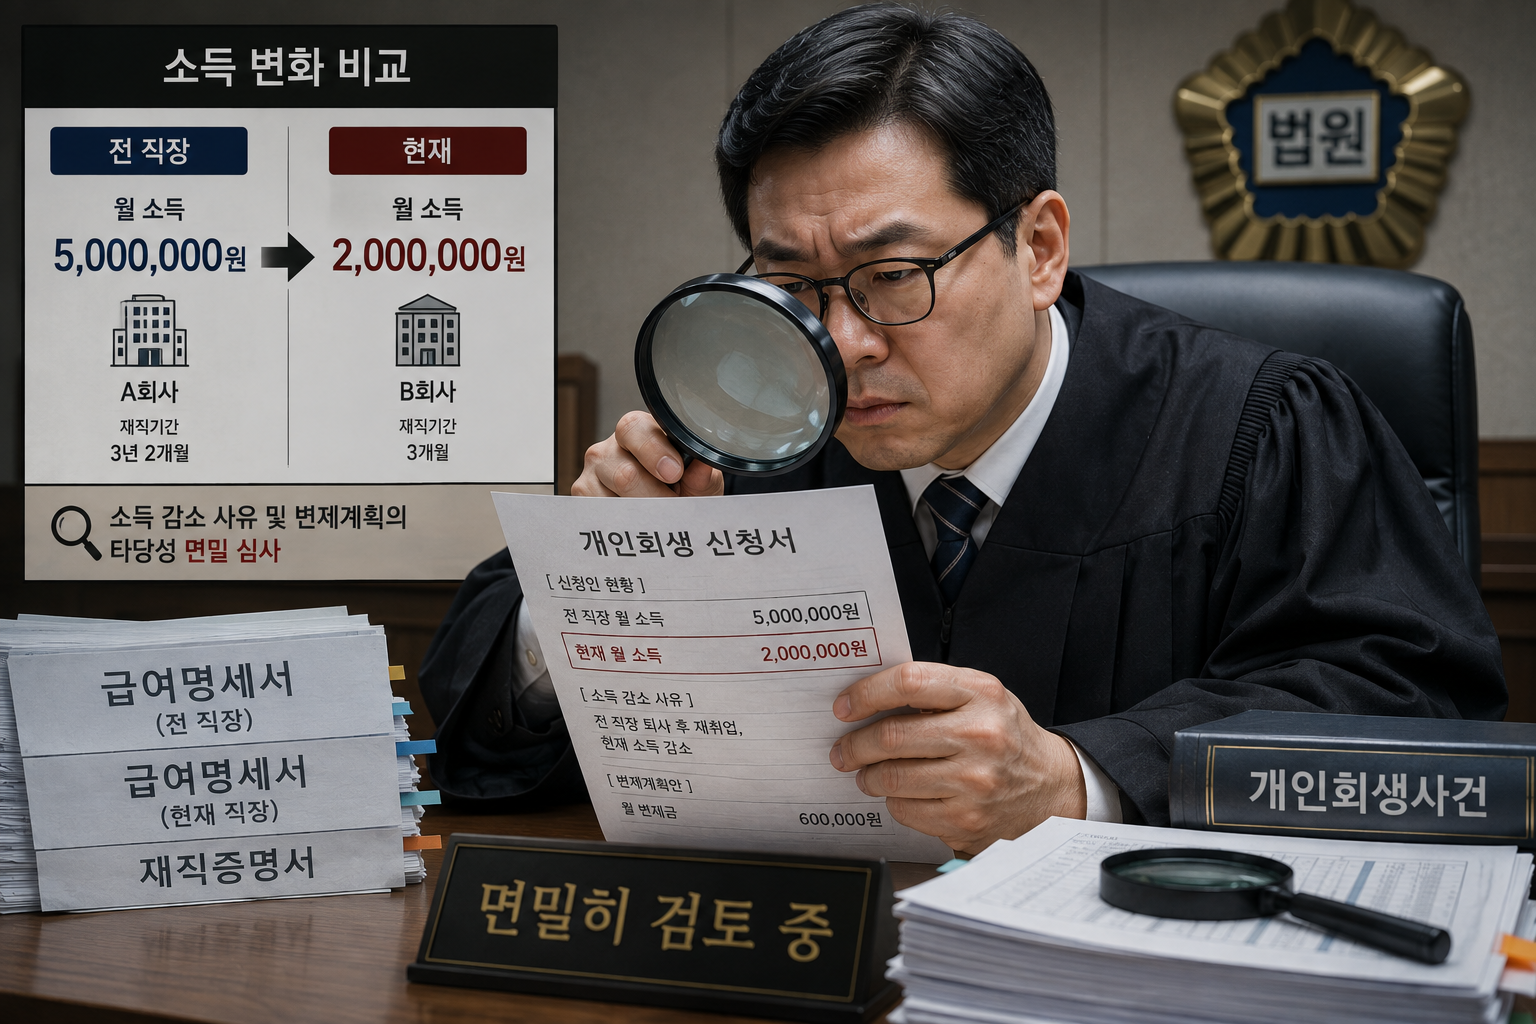
The reason for the loss decides the outcome
The court does not decide based on a single line saying you traded stocks. It looks together at how you started investing, how the losses grew, and what efforts you made afterward to repay the debt.
For example, whether you made reckless additional investments to recover lost money, whether you used loans to cover living expenses, and whether you have now stopped investing and are working diligently may all be reflected in the review. That is why it is important to explain the facts concretely without hiding anything.
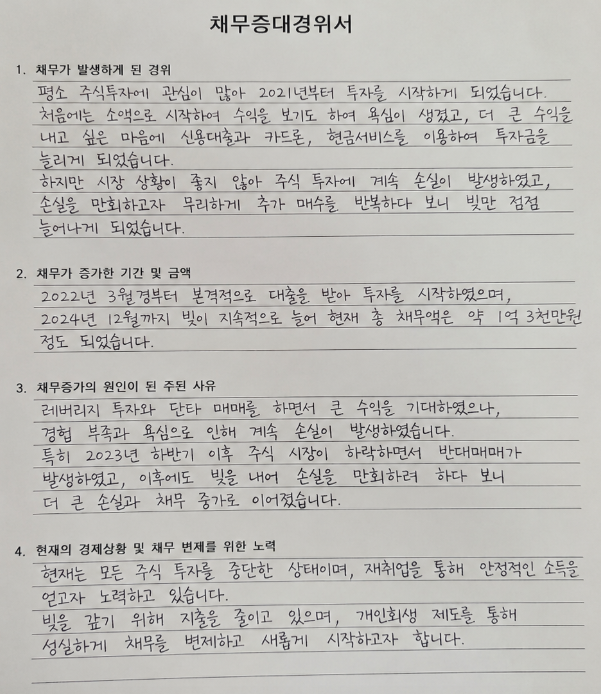
How to write the statement of how the debt increased
For debt from failed stock investments, the content of the statement of how the debt increased is especially important. Rather than a single sentence saying you lost money on stocks, setting out the following in order is more helpful in the court's review.
- Why you started investing
- How the losses occurred
- Efforts made after the losses to resolve the debt
- Your current financial situation
Actions to avoid while preparing for personal rehabilitation
- Taking out more loans to invest
- Reckless trading to make up for losses
- Investing through an account in a family member's name
- Hiding assets or making false declarations
Such actions can work against you in the personal rehabilitation procedure.
Materials to prepare in advance
For stock investment debt, the court checks transaction records and the flow of funds more often than for living expense debt. Organizing the following materials helps reduce correction orders and keep the procedure moving smoothly.
- Securities account transaction records
- Deposit and withdrawal records
- Materials showing where loan money was used
- The statement of how the debt increased
Summary
Having failed stock investments does not make personal rehabilitation impossible. The focus of the court's review is how the losses arose, your current ability to repay, and whether you can keep to the repayment plan going forward. Rather than spending time alone, we recommend first checking a solution that fits your situation.
Last reviewed: 2026-10-19 This article provides general legal information; specific advice is given through consultation.
Tell us what is happening first
Leave an inquiry and we will explain how to proceed after reviewing it. If it is urgent, please call 1577-0448.