
Personal Rehabilitation for Public Servants: Disadvantages, Pension Loans and Mutual Aid Association Loans
Public servants, school staff and military personnel have stable incomes and may seem far removed from personal rehabilitation, but quite a few people in these occupations do in fact prepare for it. What sets personal rehabilitation (gaein hoesaeng) for public servants apart from that of ordinary employees is how pension loans and mutual aid association loans are handled. Below we set out, in question order, the two loan structures you must check before filing and whether these occupations really face disadvantages.
Can pension loans also be discharged through personal rehabilitation?
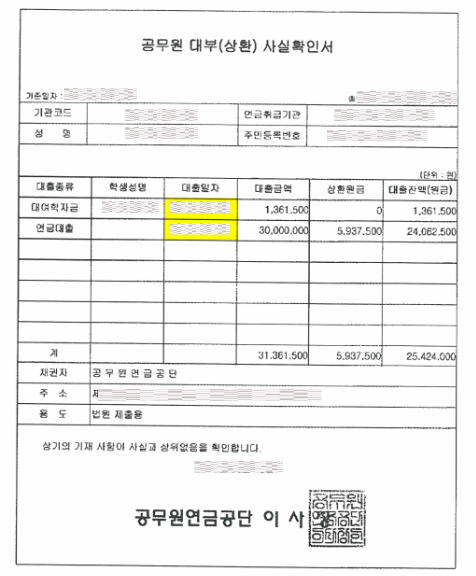
Pension loans taken from the Government Employees Pension, the Private School Teachers' Pension or the Military Pension are included as ordinary claims in personal rehabilitation. Up to this point they look the same as ordinary loans, but there is one decisive difference.
A special act applies to pension loans, so they can be deducted first from your severance benefits when you retire. This means a pension loan does not vanish completely just because personal rehabilitation has ended.
That is why, in practice, this is often noted separately in the proposed repayment plan.
Who do I end up repaying a mutual aid association loan to?
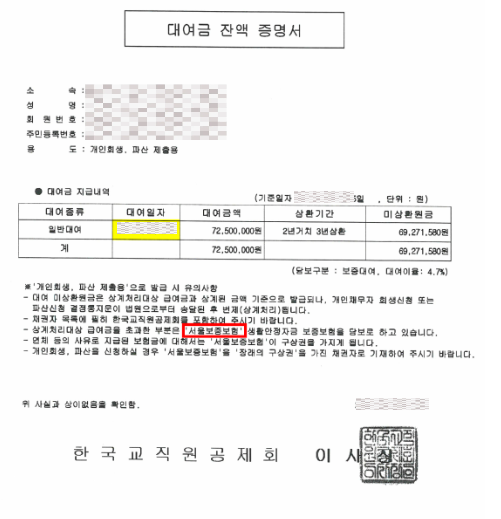
Public servants, school staff and military personnel often use loans from mutual aid associations such as the Korean Teachers' Credit Union and the Military Mutual Aid Association. Because guarantee insurance is involved in these loans, they are processed differently from ordinary loans.
When you file for personal rehabilitation, a mutual aid association loan changes in the following order.
- Filing for personal rehabilitation
- Salary deductions stop under a prohibition order
- Withdrawal from the mutual aid association is processed
- Your accumulated savings in the association are set off against the loan
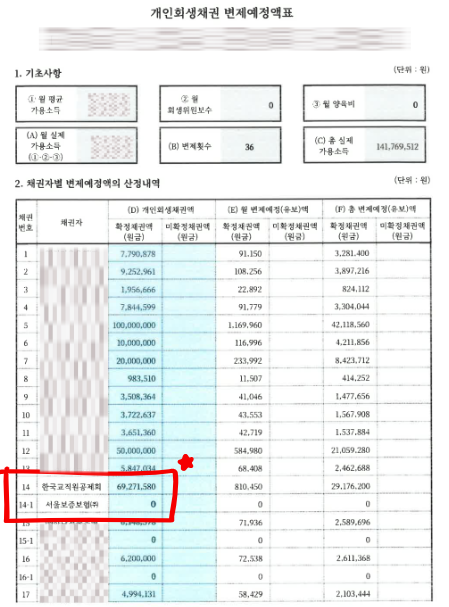
- The remaining debt passes to SGI Seoul Guarantee
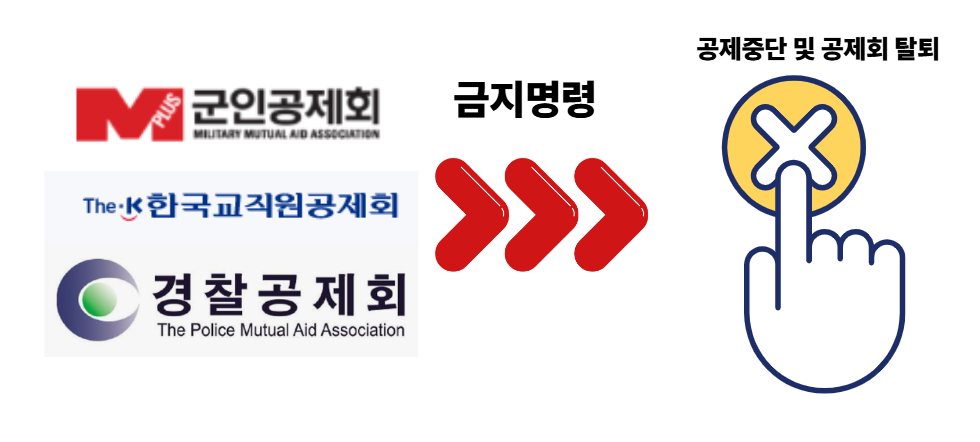
You may be withdrawn from the association automatically, and because your accumulated savings are set off against the loan, it is hard to get them back. After that, the creditor is no longer the association but the guarantee insurer.
What happens if SGI Seoul Guarantee is left off the list of creditors?
This is the most important point in practice in personal rehabilitation for public servants. When drawing up the list of creditors, you must include SGI Seoul Guarantee. If it is left out, that debt risks being excluded from discharge, and the claim may surface separately later and complicate the procedure. This is a mistake that happens often.
Do public servants face disadvantages in personal rehabilitation?
Quite the opposite. Stable employment, clear proof of income and a high likelihood of completing repayments are factors the court views positively. As long as pension loans and mutual aid association loans are properly sorted out, the procedure often goes more smoothly than it does for ordinary employees.
Summary of personal rehabilitation for public servants
- Pension loans are not fully discharged through personal rehabilitation, and any remaining amount may be deducted from severance benefits.
- Mutual aid association loans become guarantee insurance claims after set-off.
- SGI Seoul Guarantee must not be left off the list of creditors.
- Job stability actually works in your favor in personal rehabilitation.
Personal rehabilitation for public servants, school staff and military personnel is not settled by the fact of stable employment alone; you also need to understand how the pension, mutual aid association and guarantee insurance structures work together. If you miss this, unexpected debts may remain, so the case must be designed accurately from the start.
Last reviewed: 2026-10-19 This article provides general legal information; specific advice is given through consultation.
Tell us what is happening first
Leave an inquiry and we will explain how to proceed after reviewing it. If it is urgent, please call 1577-0448.